Claims
  • Articles
  • October 2026

Tough Customer Conversations: Turning discomfort into constructive dialogue

By
  • Lizzy Lubczanski
Skip to Authors and Experts
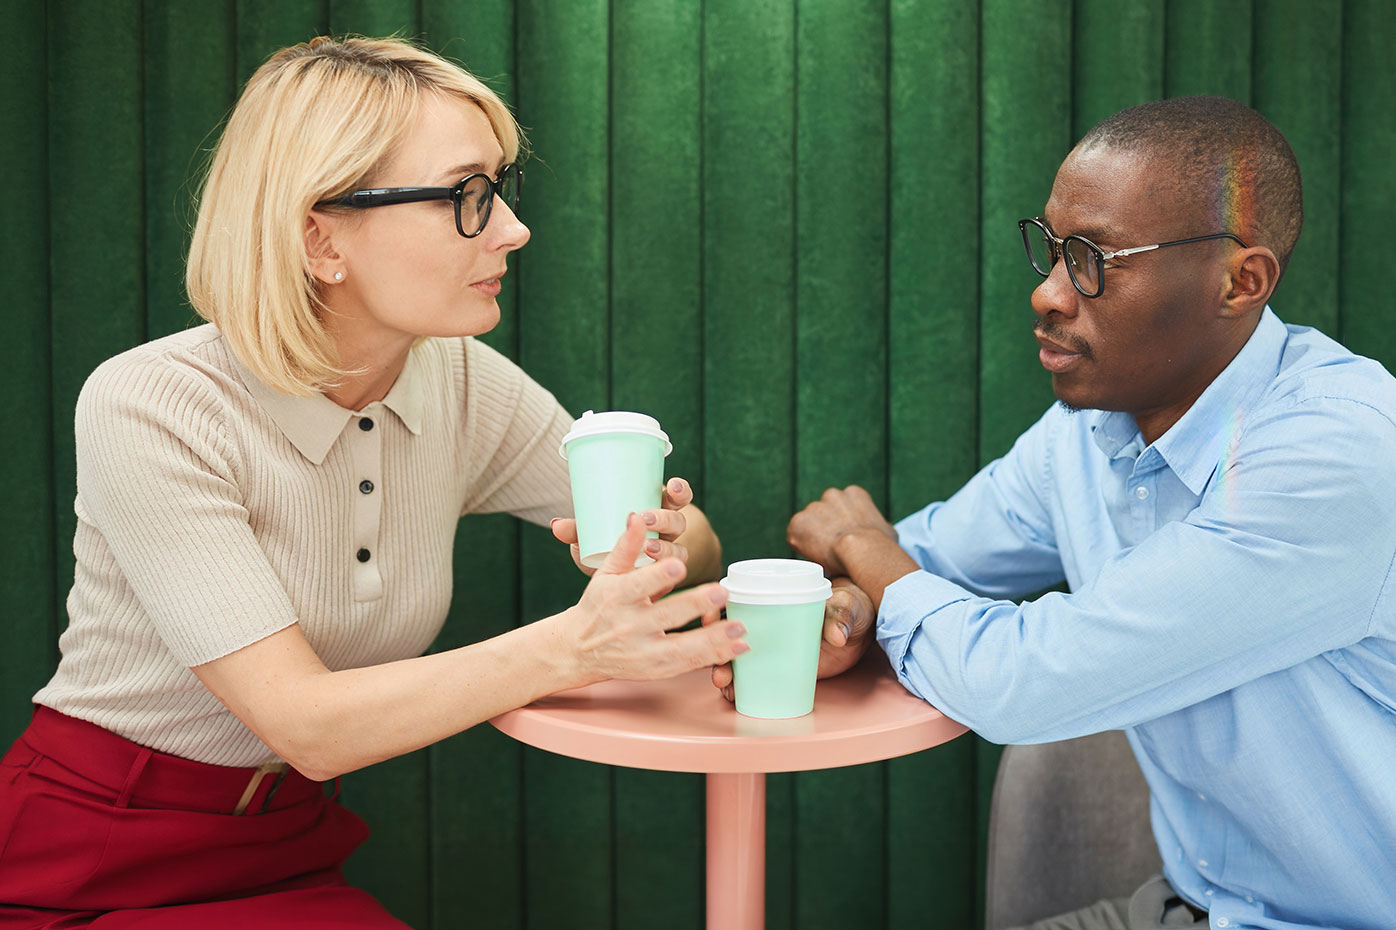
Two people talking
In Brief

Difficult claims conversations often carry emotional weight for the claimant and assessor. Behavioral science offers practical ways to reduce any threat, build trust, and simplify communication so customers can better understand what is happening and what comes next.

Key takeaways

  • Tough claims conversations can trigger emotional responses, including fight, flight, or freeze reactions, which may affect how claimants interpret and process information.
  • Claims assessors may feel pressure to soften, avoid, or over-explain unpleasant messages, making preparation and clear communication especially important.
  • Behavioral science principles can help explain the root causes of some challenging claims conversations, including non-disclosure and misunderstanding of policy information.
  • Behavioral science provides practical guidance on how assessors can reduce the feeling of threat, create a trusted messenger, and simplify the message so customers can have a better understanding and claims experience.


Setting expectations, asking for more information, or discussing a sensitive situation can be challenging for customers and assessors alike. These conversations take place at the intersection of complex policy language, personal circumstances, and real emotional impact.

Leveraging lessons from behavioral science

Behavioral science, which studies how people actually think and behave, offers a useful lens for understanding why some claims conversations can feel difficult and how they can become clearer, calmer, and more constructive. That perspective can help assessors better understand claimants’ reactions and choose communication approaches that are supportive, practical, and empathetic.

A central behavioral science idea is that people regularly move between two styles of thinking:

  • System 1 – fast, automatic, intuitive, and emotional
  • System 2 – slower, more effortful, rational, and conscious

While complex decisions, such as those involving finances or insurance, may appear to call for System 2 thinking, customers often rely on System 1. They may lean on mental shortcuts, cognitive biases, and emotional reactions as they try to navigate unfamiliar, stressful, or consequential information.

When a claimant receives unexpected bad news, the brain may interpret that moment as a threat, which can activate a fight, flight, or freeze response. Subsequent physical and mental effects may include increased heart rate, faster or shallow breathing, muscle tension, difficulty concentrating, narrowed attention, urgency, confusion, or a raised voice. Claimants may become defensive or angry, withdraw or avoid calls, or go silent because they are struggling to process what they are hearing.

Recognizing this response can help assessors avoid taking emotional reactions personally. It also reframes the assessor’s role. The goal is not simply to deliver information, but to create the conditions in which the customer can hear it. Calm, grounded communication may help reduce the feeling of threat and make space for clearer understanding.
Man looking ta computer monitor
RGA supports claims professionals with practical resources – such as the Global Claims Manual/Guide, our Pathfinder training program, and a Behavioral Science Toolkit – that build confidence, capability, and consistency.

The assessor’s perspective

Assessors can experience their own version of this pressure. Difficult conversations may create apprehension about causing distress, feeling the brunt of an emotional reaction, or being perceived as unkind. This reluctance to communicate bad news is reflected in the concept of “minimizing unpleasant message” (MUM). In practice, it can lead to messages being over-softened, difficult conversations avoided altogether, or a perceived need to over-explain. Understanding that dynamic helps assessors prepare to communicate with empathy and precision.

Assessors should also understand the cognitive biases that can shape how a claimant hears and interprets a decision:

  • Loss aversion may cause a claimant to focus more intensely on what they fear losing versus other possible outcomes.
  • Confirmation bias may lead them to notice information that reinforces an existing belief while struggling to consider alternative explanations.
  • Autonomy bias may make them uncomfortable if they feel a decision is being imposed on them rather than understood or chosen.

These are not character flaws; they are common features of human thinking under pressure. With that perspective, assessors are in a much better position to meet the claimants’ needs.

Understanding why challenging conversations occur

Behavioral science can help identify some of the root causes for the emergence of difficult claims conversations.

Customers applying for life or health insurance are typically asked to provide a medical history and lifestyle behaviors. If inaccurate information later becomes relevant to a claim, the resulting conversation may involve the need to address potential misrepresentation or non-disclosure. There are certainly instances of deliberate nondisclosure during underwriting, driven by the desire to guarantee coverage, secure favorable pricing, and/or evade awkwardness or embarrassment from revealing sensitive details.

Yet inaccurate answers can be unintentional. Question wording, memory, confusion, and the automatic nature of System 1 thinking may make it harder for customers to give complete, accurate responses.

The implication for insurance is clear: The way a question is asked can shape disclosure. Behavioral-science-based question design can reduce cognitive load, make sensitive topics feel more normal to discuss, and support more accurate responses.1,2,3

Complexity adds another layer. Insurance products, policy conditions, claims processes, and varying options can be difficult to understand. Claimants may enter a conversation having misunderstood the policy or claims process, especially if they are already under stress. This experience can be compared to being asked to enter an airplane cockpit and safely land the plane: The instruments may all matter, but guidance is necessary to understand what to do. Behavioral science can improve customers’ understanding and help them navigate complexity by building in simplicity.4,5,6

Ultimately, recognizing that challenging conversations may arise from unintentional nondisclosure and misunderstanding arms assessors with a level of understanding regarding claimants to help navigate potential tough conversations.

Watch the webinar

Difficult claims conversations are an inevitable part of claims work. In our webinar, Tough Customer Conversations: Turning Discomfort into Constructive Dialogue, Dr. Lizzy Lubczanski and RGA claims experts share practical strategies for reducing perceived threat, building trust, and communicating complex information more effectively.

Clients can access the webinar recording on demand via the Global Claims Manual/Guide. New clients who do not yet have GCM access can register here.


Guiding principles

Behavioral science offers several principles for managing tricky conversations, grounded in research and practical application. These include:

1. Give empathy

The first practical principle is to reduce the threat. This starts with empathetic communication, acknowledging emotions, using pauses, avoiding blame, and making clear that the situation is understandable. Giving customers a sense of ownership can help address autonomy bias. Helping them calmly consider different views may help manage confirmation bias. Reassurance can also come from social proof, such as explaining that others in similar situations have felt the same way, and from directing claimants to appropriate sources of support.

2. Build trust

The second principle is to be a good messenger. People give more weight to messages from someone they trust. For assessors, that means establishing credibility while remaining likeable and relatable. A claimant in a heightened emotional state may not immediately engage with logic alone. Trust built early in the conversation can make it easier for the claimant to stay engaged, feel respected, and understand the difference between a decision and the way it is communicated.

3. Make it simple

This third principle, simplification, does not mean removing important information. It means helping customers navigate complexity. Assessors can:

  • Avoid unnecessary abstraction
  • Use plain, customer-centered language
  • Provide relatable examples
  • Highlight the most relevant information at the right time
  • Break complex processes into stages

In claims calls, this may include offering options or examples rather than relying on open questions. More structured response options can make it easier for customers to answer truthfully and completely.

Conclusion

Difficult conversations are an essential part of claims work. Behavioral science offers usable principles that can make a meaningful difference for: how customers may process information, how assessors may respond under pressure, and how small changes in communication can make the experience more constructive.

By reducing threats, building trust, simplifying the message, and applying behavioral science to mitigate the root causes of difficult conversations (as described above), claims professionals can approach challenging conversations with professionalism, empathy, and purpose.


More Like This...

Meet the Authors & Experts

Lizzy Lubczanski
Author
Lizzy Lubczanski

Lead Behavioral Scientist

References

  1. https://www.rgare.com/knowledge-center/article/improving-mental-health-disclosures-for-insurance-underwriting
  2. https://www.rgare.com/knowledge-center/article/improving-smoking-and-alcohol-disclosures-using-behavioral-science
  3. https://www.rgare.com/knowledge-center/article/bringing-order-to-complexity-in-claim-forms-an-rga-behavioral-science-study
  4. https://www.rgare.com/knowledge-center/article/how-behavior-aware-design-can-boost-annuities-for-retirees
  5. https://www.rgare.com/knowledge-center/article/from-complexity-to-confidence--applying-behavioral-science-to-annuity-decisions
  6. https://www.rgare.com/knowledge-center/article/video--selling-simplicity-in-insurance