Two stages, not one
A useful starting point is to reframe retirement as two broad stages.
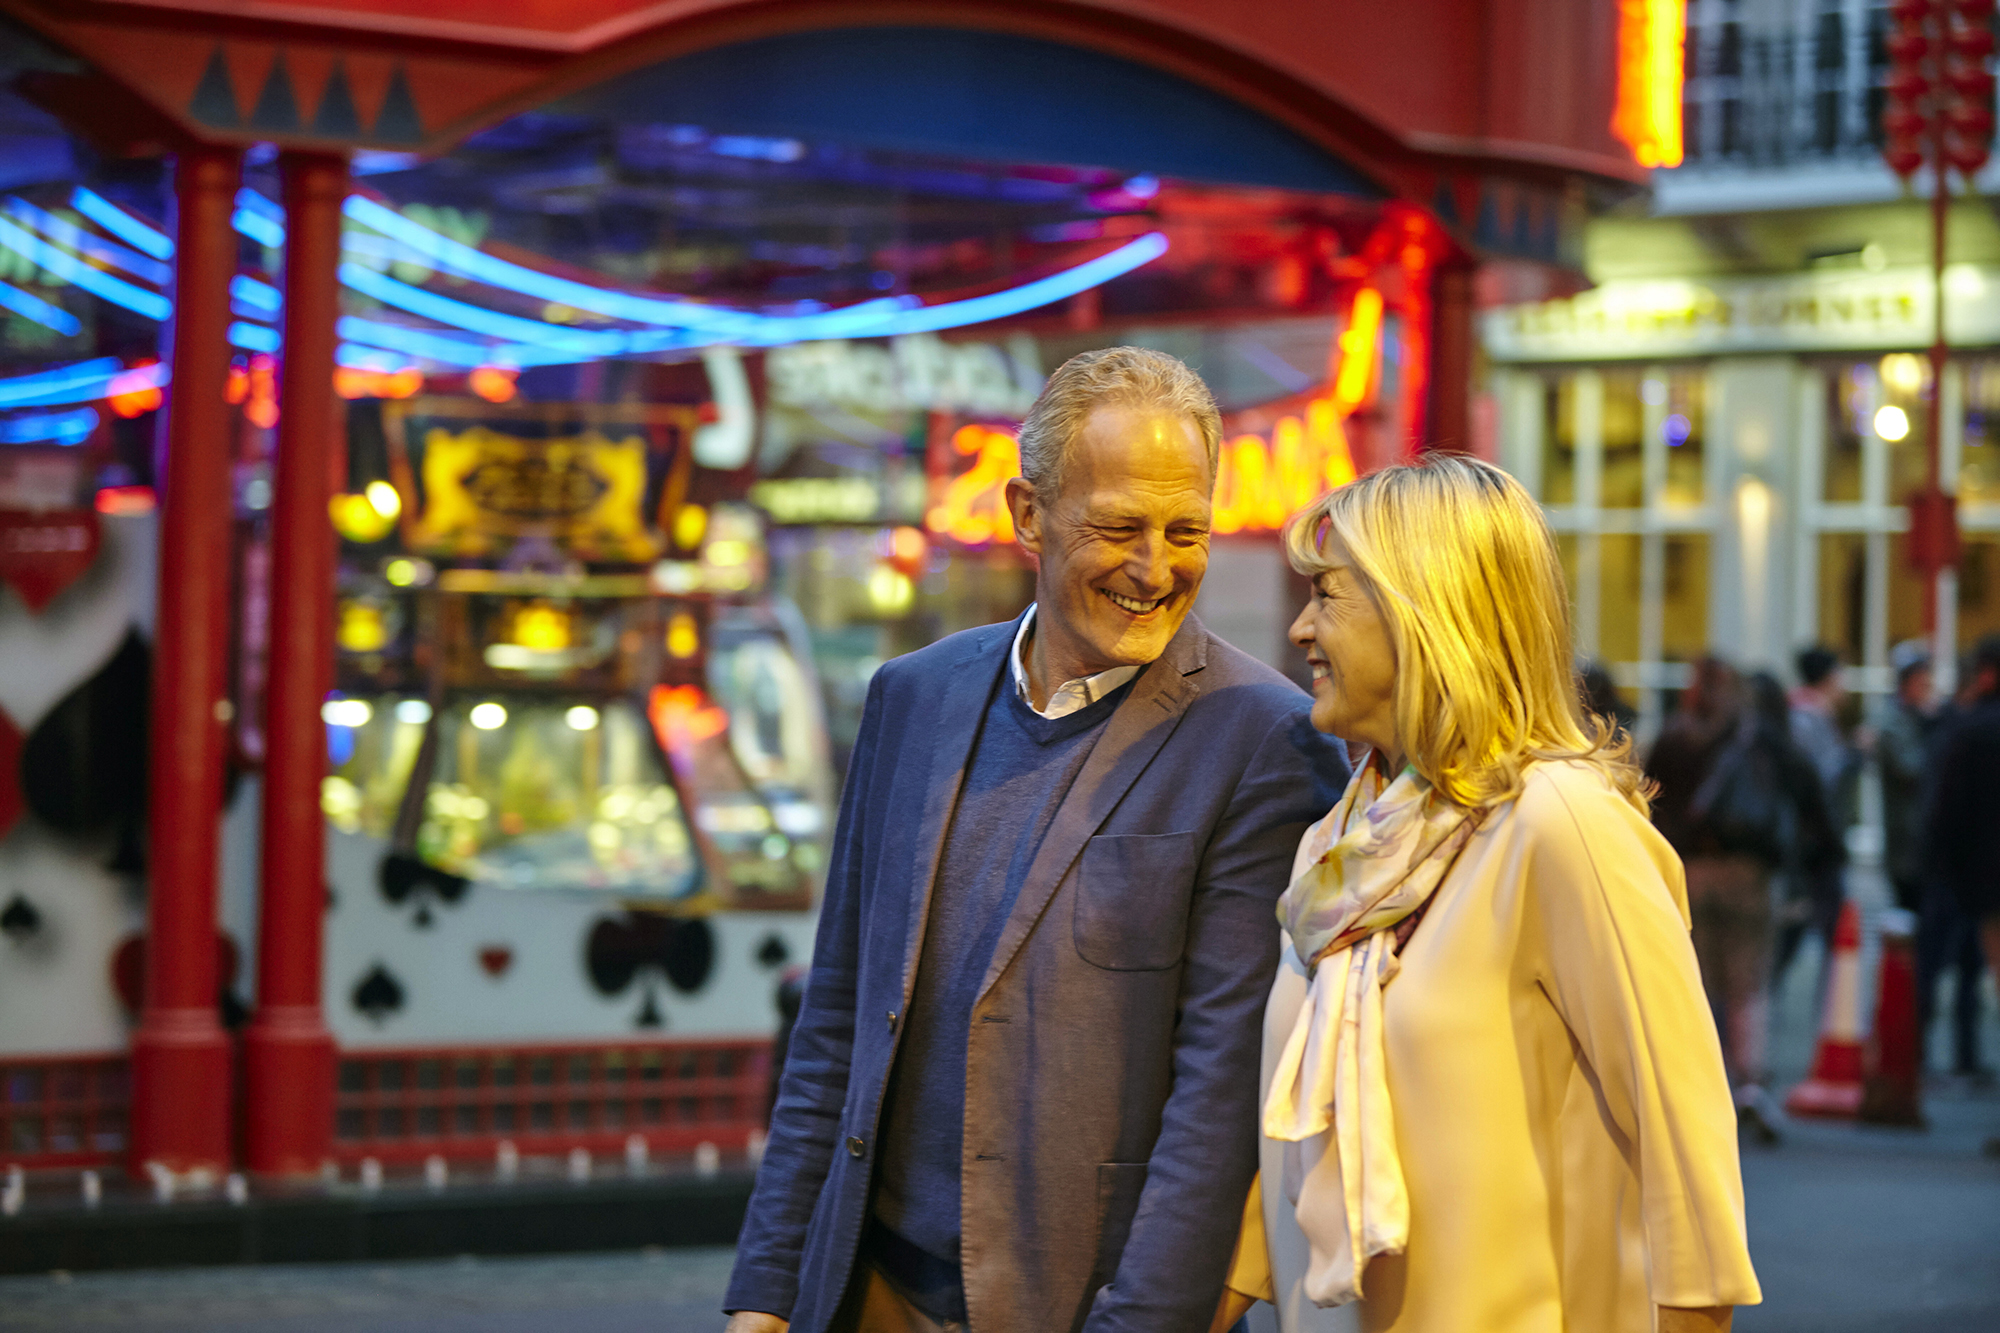
- The first stage can be thought of as “wining and dining.”2 This is the period immediately following retirement when health is generally good and retirees have both the ability and desire to spend on discretionary activities. Travel, hobbies, dining out, and helping family members may feature prominently. Spending is often flexible and lifestyle-oriented.
- The second stage is “heating and eating.”2 In later life, spending typically becomes less discretionary and more focused on essentials. Utility bills, food, and everyday living expenses take precedence over travel and entertainment. Physical health may be declining, financial resources may be more limited, and managing investments may become increasingly burdensome.
These descriptions are deliberately broad. No two retirements look exactly alike. Some individuals may spend many years in the first stage, while others may move relatively quickly into the second.
Nevertheless, viewing retirement through this lens acknowledges a fundamental reality: Spending needs, health, and financial priorities change over time.
The distinction is supported by evidence from healthy life expectancy statistics. Many retirees can expect a decade or more of relatively healthy retirement before entering a period in which declining health becomes a more significant factor.3 While individual outcomes vary substantially, especially across socioeconomic and geographic groups, the existence of these two broad phases creates a useful framework for thinking about decumulation.
Matching products to retirement needs
After dividing retirement into two stages, the next question is clear: Which products best fit each phase?
The proposed answer is a flex-then-fix approach.
The first phase favors flexibility. Income drawdown allows retirees to keep assets invested while accessing funds as needed. For retirees who remain healthy, active, and financially engaged, drawdown resembles the budgeting decisions they have made throughout their working lives. It provides the ability to adjust spending, react to changing circumstances, and maintain access to capital.
Flexibility has value.
A retiree planning an extended holiday, helping a child purchase a home, or responding to unexpectedly high expenses may appreciate the ability to vary withdrawals over time. Drawdown supports this freedom in a way that guaranteed income products generally cannot.
However, flexibility comes with responsibility. The retiree bears investment risk, longevity risk, and the possibility of spending too much too soon. Managing those risks successfully requires ongoing engagement and decision-making.
That reality makes drawdown a strong candidate for the first stage of retirement, but a less obvious fit for the second.
The case for fixing later
As retirement progresses, certainty often becomes more valuable than flexibility.
In the later stage of retirement, essential expenses continue regardless of market performance. Utility bills still arrive. Groceries still need to be purchased. Housing costs still exist. At the same time, the desire or ability to actively manage a retirement portfolio may decline.
This is where the “fix” component of the framework becomes relevant.
A lifetime annuity converts a portion of accumulated retirement savings into a guaranteed stream of income that continues for life. In exchange for surrendering flexibility and liquidity, retirees gain protection against one of retirement's greatest uncertainties: outliving their money.
Importantly, the flex-then-fix framework does not position annuities and drawdown as competitors. The retirement industry often treats them as opposing choices, forcing retirees into an either-or decision. In reality, the strengths of one product tend to complement the weaknesses of the other.
- Drawdown provides flexibility but lacks certainty.
- Annuities provide certainty but lack flexibility.
Combining both over the course of retirement creates the potential for a more balanced outcome than relying exclusively on either product.
Emerging retirement collective defined contribution (R-CDC) solutions may also become part of the future UK decumulation landscape. While these products offer lifetime income, their income levels may fluctuate based on fund performance. For retirees seeking to match predictable expenses with predictable income, annuities currently offer a clearer alignment with later-life spending needs.
The most important question: When?
If flex-then-fix is the framework, the critical question is determining when the transition should occur.
There is no universal answer.
The timing will depend on health, wealth, spending patterns, market conditions, and individual objectives. However, three useful signposts may help guide the decision.
The question of “when” deserves greater attention from policymakers, insurers, and pension providers. The industry's focus has largely and justifiably been on helping individuals accumulate retirement assets. If people have enough savings, decumulation becomes less of a concern, and if people don’t have enough savings, it can be challenging to find a successful decumulation strategy.
That said, helping retirees identify the optimal point to transition from flexibility to certainty may prove equally important. Further research into discovering this point is an important task for our industry to tackle now.
Conclusion: A better framework for a new retirement reality
The UK's retirement system is evolving rapidly. Pension freedoms expanded choice and flexibility, but greater choice has also created greater complexity. Many retirees are now required to solve an extraordinarily difficult financial puzzle with limited guidance in their attempt to create the best of times in their golden years.
The flex-then-fix model offers a simple but powerful reframing of that challenge. Rather than treating retirement as a single event, it recognizes retirement as a journey.
Early retirement often benefits from flexibility and personal control. Later retirement often benefits from certainty and protection.
No framework can fully eliminate uncertainty. Health, markets, longevity, and personal circumstances will always remain unpredictable. Yet retirement planning does not require perfect answers to be valuable and to avoid worst-of-times scenarios. It simply requires a structure that helps people make better decisions.
By aligning retirement products with the realities of how retirement changes over time, flex-then-fix provides a practical framework for navigating one of the most difficult financial decisions individuals will ever face. And as DC pensions continue to expand globally, that framework may become increasingly relevant far beyond the UK.
RGA offers its partners a highly tailored experience for each and longevity risk partnership. Learn more about the solutions we offer and how a partnership with RGA can benefit your business.